Want to be in the loop?
subscribe to
our notification
Business News
ADMINISTRATIVE REFORM NEEDED FOR BETTER ACCESSIBILITY TO CREDIT
Vietnam's access to credit has improved significantly and remained stable among the top 30 countries. In the Doing Business Report 2018 released by the World Bank (WB), the country’s Getting Credit Index ranked 29th out of 90 countries, lower than that of Malaysia and Cambodia at 20th and on par with Singapore but higher than that of Thailand (42), Indonesia (55), Laos (77) and the Philippines (142).
According to the WB and the World Economic Forum (WEF), Vietnam's credit access index also had a considerable pickup thanks to solutions adopted by the State Bank of Vietnam (SBV) in the past time.
Mr Nguyen Duc Long, Director of the SBV Forecasts and Statistics Department, said, as for the depth of credit information, this index has risen sharply from 4/6 in 2013 to 7/8. The only criterion that Vietnam has not reached relates to credit information. In addition to information of borrowers having relations with credit institutions, there is no information of borrowers dealing with retailers or service providers (such as electricity, water and sanitation).
Vietnam has little improvement in the legal strength index in nearly 10 years. It stayed unchanged at 8/10 from 2010 to 2014 and at 7/12 on a new scale from 2015 to 2017 and climbed to 8/12 in 2018. This index reflects legal rights and interests of lenders and borrowers, assesses how legal regulations on bankruptcy and guaranteed transaction protect lenders and borrowers to boost lending activity. Four indexes that Vietnam have not yet reached largely relate to legal interests that protect lenders.
Dr Vu Tien Loc, President of the Vietnam Chamber of Commerce and Industry (VCCI), said, what the banking sector can do for the economy is more than numbers. At present, 80 per cent of credit is channelled into production and business. Credit supplied to BOT is stable and tends to decrease.
He added that, in other countries, medium and long-term funds are provided by capital and stock markets, not banks. Meanwhile, in Vietnam, 55 per cent of medium and long-term capital is supplied by banks.
In fact, well-profiled businesses and customers can easily access credit at reasonable interest rates for their good business projects and plans. In 2017, credit growth was 18.24 per cent. Corporate and personal borrowers can approach bank loans more easily, evidenced by more convenient and quicker product and service processes for customers, powered by information technology (e.g. Internet Banking and Mobile Banking). According to statistics, the time, number of transactions and documents provided by customers have decreased by 20-40 per cent; a number of processes to products/services fell by 42 per cent; customer signatures dropped by 45 per cent; banker signatures declined by 48 per cent; and registration time plunged 70-75 per cent as a result of electronic formalities.
To improve other indicators, a voluntary coordination between providers of electricity and other services with the National Credit Information Centre in providing additional borrower information is necessary, according to Mr Long.
Besides, in order to expand credit access, apart from solutions from the banking sector, companies necessarily restructure their operations, boost their financial capacity and build up the confidence of credit institutions. At the same time, there is a strong need for coordinated efforts of central and local authorities and industries in executing measures to support enterprises to deal with emerging production and business difficulties as guided by the Government like further speeding up SME development support plans; building the capacity of units that deliver assistances for SME development; reviewing and removing difficulties against enterprises; simplifying administrative procedures concerning tax, land and construction investment affairs; effectively carrying out incentives for companies to expand production and business operations.
Dr Vu Tien Loc, VCCI Chairman & President
Agriculture and business start-up are two most important paths for the development of the Vietnamese economy but these two fields find it hard to access to credits. And, creating a legal framework and institutional system to facilitate lending to these two fields is the responsibility of not only the banking sector but also of the National Assembly and the Government.
Indeed, the current legal framework and land policy prevent agribusinesses and start-ups from accessing credit. Some have complained that they have thousands of hectares of land for cultivation and production but they cannot use such land for securing loans because only factories are taken into consideration. Meanwhile, factories are not important and advantageous factors of agribusinesses.
Therefore, how to change lending forms to enable agribusinesses to mortgage their land, crops, livestock and projects - their future cash flows - for their loans is very important now. This is a weapon for them to clear difficulties in the way to development.
At the same time, there is a need for breakthrough supports for businesses, especially micro, small and medium agricultural businesses and startups.
Mr Nguyen Quoc Hung, Director of Credit Department, SBV
As for small and medium-sized enterprises (SMEs), many fail to meet borrowing conditions because of their infeasible business plans, limited owner equity and financial capacity, unprofessional accounting, non-transparent financial information and insufficient security assets.
Notably, credit performance in SMEs is not high because they have small scales and weak management in addition to limited scientific and technological applications.
Before the Law on SME Support and guiding documents for enforcement are issued, SME support policies on credit access are still weak and ineffective, failing to help SMEs to access credit sources.
For their part, credit institutions must apply reasonable interest rate policies and meet many objectives at the same time such as ensuring a real profit margin for depositors and offering incentives for key credit programmes. Besides, lending must comply with the law and ensure effectiveness and safety of loans granted.
However, banks have not really competed with service quality but with interest rates amid growing competition.
Meanwhile, risks of people and businesses in marketing, natural disasters and epidemics are also risks of credit institutions because such pains hurt their repayment capacity.
Mr Mac Quoc Anh, Vice Chairman and Secretary General, Hanoi SME Association
The survey conducted by our association showed that 59 per cent of SMEs are rejected by banks or only partially lent.
For the time being, six barriers are standing against SMEs on path to credit. Firstly, the currently available state budget is still scant. Some support programmes and packages have not brought in desired results such as training, market, introduction of scientific and technological products and trade promotion. Secondly, information about SMEs lacks transparency and reliability.
Thirdly, SMEs’ loans can easily lead to bad debt because collaterals are unconvincing, resulting their narrow access to bank loans. Fourthly, SMEs do not pay much attention to training, consultancy and information from support programmes but mainly from informal channels. Thus, they lack updated policy information and are easily affected by external factors.
Fifthly, SMEs have weak governance, backward technology and non-transparent information. They lack borrowable requirements. Finally, some credit institutions are not interested in SMEs but because of their small scale, poor credit performance and long appraisal amid high risks and operating costs.
To break down such barriers and improve credit accessibility for SMEs, it is necessary to further upgrade the business environment, enhance national competitiveness, support and facilitate business development. Credit institutions continue to conduct reviews to seek for more welcoming loan procedures in order to provide most favourable conditions for customers, adopt measures to remove difficulties in credit relations with enterprises. At the same time, they necessarily attach importance to diversifying credit products for SMEs, foreign currency products and risk-averting tools for interest rates and exchange rates to help customer companies to have more available credit sources and simplify lending processes.
Dr Can Van Luc, Banking specialist, BIDV
At present, six capital sources are available for businesses: State budget (guarantee, insurance, interest rate support, support fund, etc.); foreign capital; funds from capital markets (securities, bonds); business partners; credit, guarantee, discount and finance lease; and finally equity capital, equity contribution and share sale.
Businesses now seem to be forgetting a major source: Finance lease. Over the past years, the State has made efforts to promote this form but its scale is still small at present. Just 12 financial leasing companies with a balance of VND10 trillion is too small for the current number of SMEs. Leasing services do not require collaterals.
To enable businesses to access credit capital more effectively, some solutions are needed. The State Bank of Vietnam should speed up credit institution restructuring in combination with dealing with bad debts in 2016-2020.
For their part, credit institutions necessarily design specific products suitable for each customer segment and boost lending with designed credit packages. They need flexible measures on security assets (accept non-property assets); provide more services (consultancy, training, information, workshop, etc) for customers; accelerate information technology application, digital finance, especially borrower information and database management. They should support customers to increase their knowledge of finance and credit through training.
Meanwhile, businesses should have transparent operation and financials; increase its cooperation goodwill with credit institutions in supplying information; restructure debts; and formulate appropriate business plans.
Source: VCCI
Related News
GARMENT / TEXTILE
GARMENT, TEXTILE INDUSTRY LOOKS TO AI, ROBOTS TO BOOST COMPETITIVENESS
The textile and garment industry is seeking to accelerate the adoption of artificial intelligence (AI), robotics and automation to improve productivity, meet increasingly stringent international standards and move towards higher value-added production. Đỗ Nam Bình, deputy director of the Industry Agency under the Ministry of Industry and Trade, said textiles and garments remained a strategic sector of the Vietnamese economy with significant contribution to export earnings, job creation and the country’s integration into global supply chains.
VIETNAM MONTHLY STATISTICAL DATA
INFOGRAPHIC SOCIAL-ECONOMIC PERFORMANCE IN OCTOBER OF 2026
The monthly statistical data presents current economic and social statistics on a variety of subjects illustrating crucial economic trends and developments, including production of agriculture, forestry and fishery, business registration situation, investment, government revenues and expenditures, trade, prices, transport and tourism and so on.
CHARITY / EXHIBITION / OTHER EVENTS
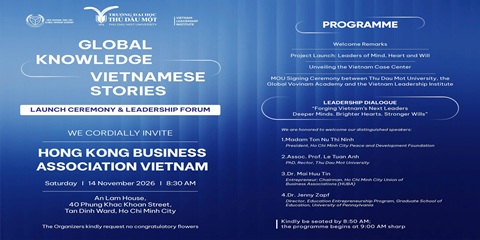
INVITATION | GLOBAL KNOWLEDGE - VIETNAMESE STORIES
The Organizing Committee is pleased to cordially invite you to attend the program “Global Knowledge – Vietnam Stories”, hosted by Thu Dau Mot University, in partnership with Global Vovinam Academy and Vietnam Leadership Institute. The program will feature a Partnership Announcement Ceremony and a Leadership Dialogue under the theme “Forging Vietnam's Next Leaders: Brighter Hearts. Stronger Wills. Deeper Minds."

MEMBER CORNER / PROMOTIONS
FLY TO HONG KONG WITH A USD40 OFFER FROM CATHAY PACIFIC
From familiar sights like the iconic ding ding trams to the breathtaking Victoria Harbour, think you’ve seen it all? Venture beyond the usual to uncover local neighbourhoods, an ever-evolving culinary scene, and vibrant festivals that define this Asia's World City. This November, experience the energy of one of the world’s most unique destinations with Cathay Pacific with promo code FLYTOHK40 for USD40 off on flights to Hong Kong.
GARMENT / TEXTILE
VIETNAM MANUFACTURING GROWTH EASES IN OCTOBER AS EXPORT ORDERS FALL
The S&P Global Vietnam Manufacturing Purchasing Managers' Index ticked up to 52.3 points in October from 51.9 points in September, pointing to a further modest monthly strengthening in the health of the sector at the start of the fourth quarter. Business conditions have now improved in 16 consecutive months. The overall improvement in operating conditions was limited by slower rises in output and new orders.
INFRASTRUCTURE / CONSTRUCTION / LOGISTIC / PORT
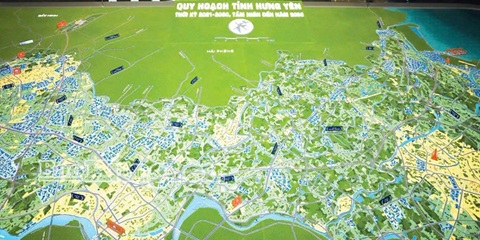
HUNG YEN BOOSTS INFRASTRUCTURE TO TAP COASTAL GROWTH POTENTIAL
Hung Yen is shaping its development space to connect the northern industrial and urban areas with the coastal economic zone. Under the provincial master plan for the 2021–2030 period, with a vision to 2050, as adjusted under Decision No.579/QD-UBND, the province has established a structure comprising three regions, two corridors, three longitudinal axes, and four horizontal axes.
Events Sponsors